Your first home
Clear explanations of the parts nobody explains: financing conditions, inspections, strata documents and closing costs. Room to ask questions before making a commitment.
Buy with us
A good search gets more precise as it goes. We bring local knowledge, financial discipline and a close reading of the home to every decision.
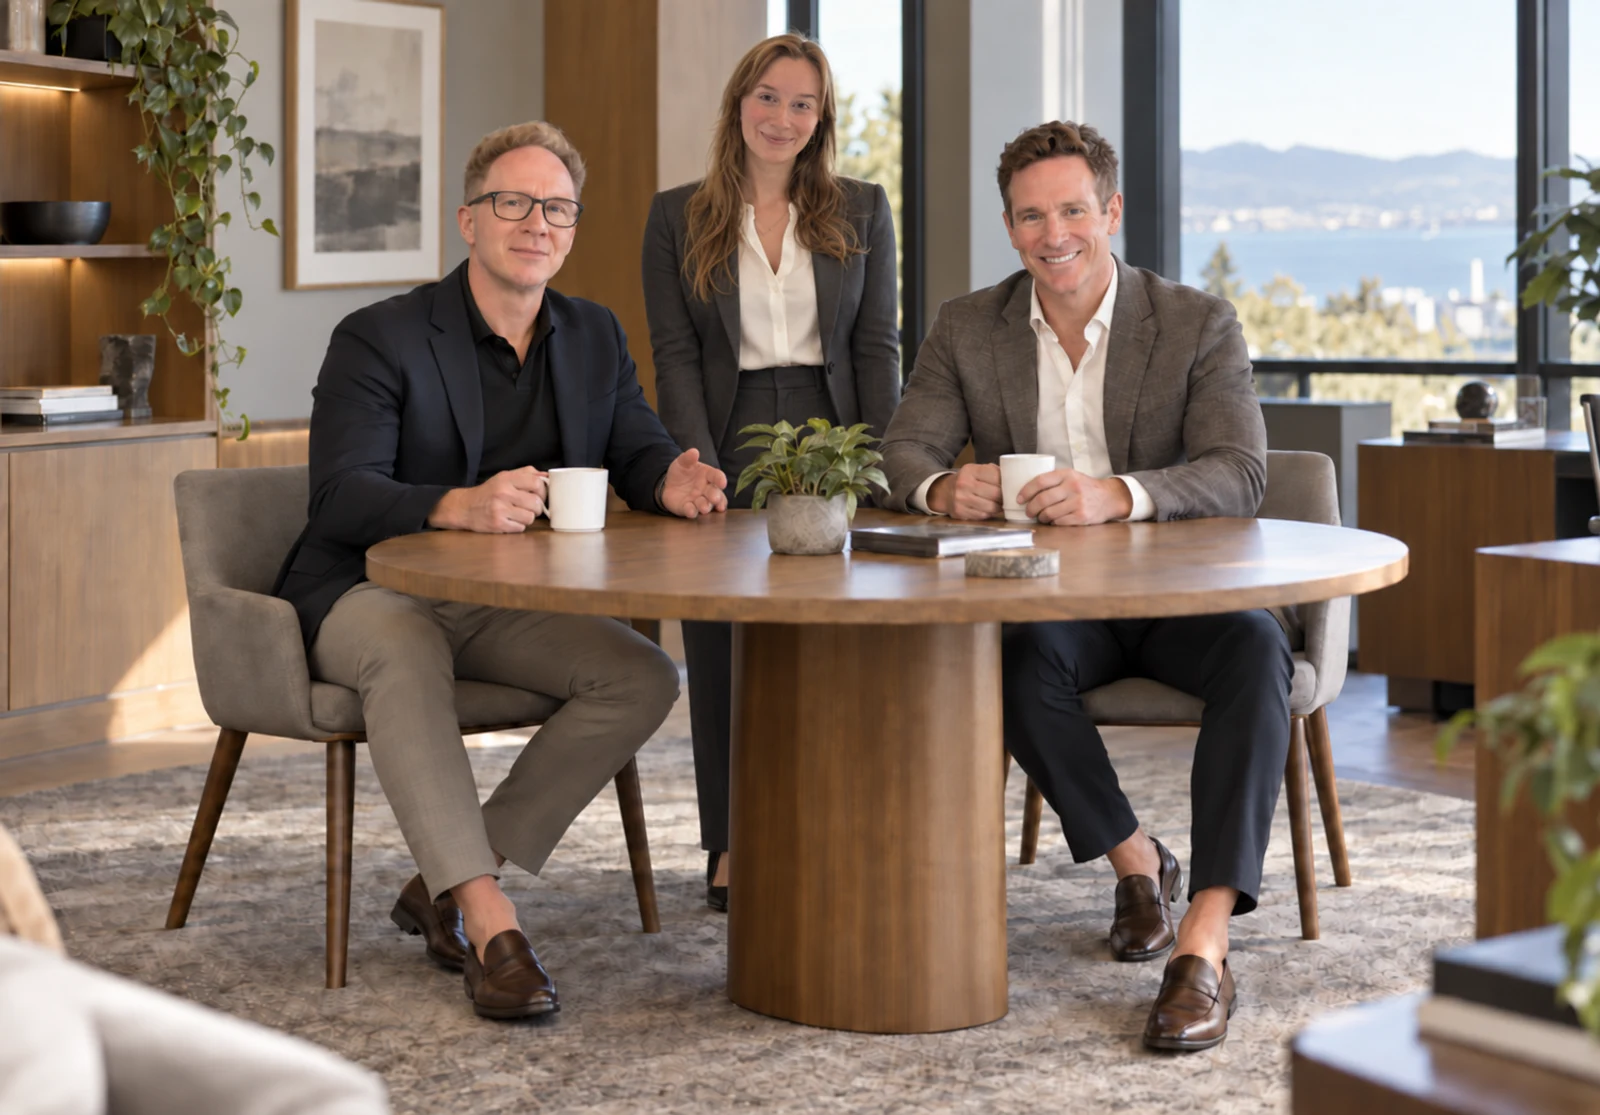
Derek GilletteWorking alongside associate Chris Sinclair,
supported by Kyra Gillette in client care.
In Chris’s words
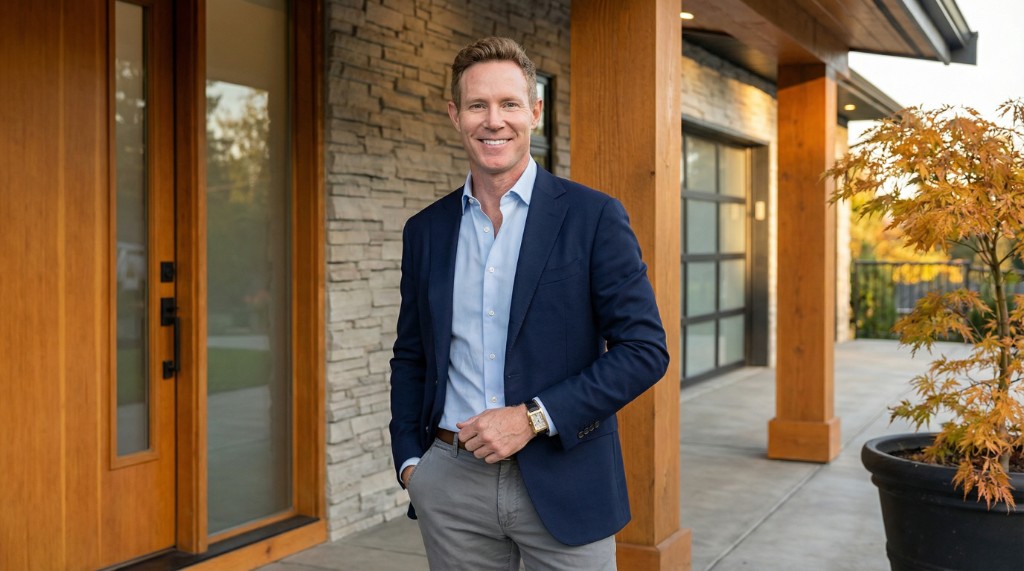
“My job is to help you see what the asking price doesn’t tell you.”
My background is in business. I hold an MBA, and I use it. Knowing what a house sold for down the street matters. I also want to understand why.
I follow the wider economy: how interest-rate decisions can affect borrowing, how migration shapes demand, and what those changes might mean for a neighbourhood over time. Real estate happens inside an economy. I pay attention to both.
Then I look closely at the home itself. Does the asking price stand up to the evidence? How long has it been on the market? Which comparable actually compares? I watch the local market closely because the details can change the decision.
Whether this is your first purchase, an investment or a move to the Island, I’ll give you an honest second opinion. If a property isn’t right, I’ll say so. If it makes sense to wait, we’ll talk about that too. Trust is something I try to earn on every call, every showing and every offer.
More about ChrisWherever you’re starting
Clear explanations of the parts nobody explains: financing conditions, inspections, strata documents and closing costs. Room to ask questions before making a commitment.
A close look at the numbers and the assumptions behind them. Purchase costs, ongoing expenses, potential income and resale considerations belong in the same conversation.
When you can’t be here, Chris can be your eyes on the ground and your honest second opinion. Local context, a careful look at the property and a clear account of what he finds.
The working order
Five stages, with enough room to change your mind when the evidence changes.
We turn budget, timing and daily life into a useful search, with room for the brief to change.
Recent sales and current competition establish what the asking price does and does not tell us.
We compare condition, setting and value while the details are still fresh enough to be useful.
Financing, inspection, title and documents get the time and specialist attention they require.
Price, dates, subjects and leverage are considered together before anything is signed.
Useful before we meet
The buyer handbook · British Columbia
Buying your first home in Nanaimo or on Vancouver Island? You don’t need to know all the terms. Start where you are, see what happens next, and take it one step at a time.
Search the handbook, or choose a topic below.
Choose a step to see what happens, what you need to do, and what it looks like for a first-time buyer.
Step 1 of 6 · Plan your budget
Start with a comfortable monthly cost, then work back to a price range. Leave room for the expenses of buying and owning.
Alex starts by checking a comfortable monthly budget and the first-time buyer support that may apply. Alex asks about the First Home Savings Account (FHSA), the RRSP Home Buyers’ Plan and BC property transfer tax exemptions before deciding how to use savings.
You may not be paying purchase fees yet. Start asking for estimates so they are part of your savings plan.
Some programs help you save, some let you use registered savings, and others may reduce tax. Each has its own eligibility rules and timing.
Step 2 of 6 · Look at homes
Tour homes with your priorities in mind. A home can look right and still need careful checks before you commit.
Alex likes a townhouse. The next questions are about monthly strata fees, building repairs and records, not just whether the furniture fits.
Travel and viewing take time. Research inspection, document and specialist costs before you need them.
Found a home you want to pursue? Your representative helps turn your intentions into a written offer.
Step 3 of 6 · Write your offer
Your offer proposes the price, dates, and other terms. Your representative should walk you through it before you sign.
Alex’s offer includes financing, inspection and -document subjects, with a proposed 10-business-day period. The agreed contract sets the exact subject-removal deadline. The exact date and time come from the contract, rather than a fixed rule.
The amount and due date must be clear in the contract. Have a plan for accessing the money on time.
If the offer is accepted, organize your checks immediately. Do not wait for the subject deadline.
Step 4 of 6 · Offer accepted
This is your due-diligence period: time to check whether the property, financing and documents work for you. In Alex’s example, the accepted contract allows 10 business days. Your own agreed deadline may be different.
Alex starts straight away. Within the agreed 10-business-day period, the lender reviews the townhouse, the inspector checks its condition, and Alex reviews the records. Questions are raised early enough to get answers before the deadline.
Inspection, appraisal or document charges can arise now. Your may also be due: follow the timing in your contract.
Once you have the answers, decide with your representative whether you can remove the .
Step 5 of 6 · Decide about subjects
Review each subject with your representative before signing a removal or waiver. Once the buyer’s are removed, the purchase is generally described as firm, provided no other conditions remain. That does not mean you can move in yet.
Alex signs the subject-removal document after the checks are complete. The home is now a firm sale in this example, but Alex does not get the keys that day. The contract has a later completion date and an agreed possession date and time.
Check the amount, due date and payment instructions in your contract so the funds are ready on time.
The home may be marked sold, but legal completion and possession are still ahead. Keep those dates in your calendar.
Step 6 of 6 · Complete & move in
Sold does not mean ready to move into. Completion is when ownership transfers and the purchase funds are paid. Possession is the agreed date and time you can take over the home. These can be different days.
Alex’s are removed first. Later, on completion day, the legal transfer and payment take place. On the contract’s possession date, at the agreed time, Alex receives the keys and can move in. These are three different milestones.
Your legal professional confirms the balance needed: remaining purchase funds, closing expenses and adjustments.
Once you’re settled, keep property records together and maintain a budget for repairs and ongoing costs.
Check the programs you may qualify for. The guide explains savings accounts, registered-plan withdrawals, tax credits, exemptions and rebates, including when to apply.
Explore your first-time buyer program map →A helpful distinction: an accepted offer can already be a binding contract, even with subjects. Subject removal is a separate decision. Ask your representative to explain your obligations before you sign.
Contract guidance: BCFSA — offers and subject clauses ↗
“Subjects” and “conditions” often mean the same thing here. You’re allowed to ask what every word means.
Requirements written into your offer that must be dealt with by a deadline. A financing subject, for instance, can give you time to confirm financing for this particular property.
“Subject to financing” does not mean your mortgage is already approved. Your representative should explain the wording, deadlines and how notice must be given.
The formal written step used to remove specified conditions from your contract. Removing a subject means you are no longer relying on that condition.
Before signing, confirm the condition is satisfied or get advice about the consequences of waiving it. A deadline is not something to leave to the last minute.
Money paid under your purchase contract, held as the contract directs and credited toward the purchase at completion.
It forms part of your purchase funds. It is not an extra amount on top of your down payment. Its amount and due date come from your contract.
The stage when the purchase funds and legal transfer are completed. Your lawyer or notary handles the legal work.
You may sign paperwork and send money before completion day. Ask your legal professional for their exact deadlines.
The date and time the contract says you can take possession of the home, commonly when keys are released.
Completion and possession can happen on different days. Book movers around the agreed possession time, not an assumption.
Amounts that divide certain property expenses between buyer and seller using the agreed adjustment date.
If the seller prepaid taxes covering part of your ownership period, your share may be added to the funds you need at closing.
Third-party expenses your legal professional pays as part of the purchase, usually listed separately from their service fee.
These may include registration and search charges. Ask for an itemized quote, including taxes.
An early lender assessment that helps you plan a price range. It is not the same as final approval for a particular purchase.
The lender still needs to assess the property and confirm its requirements. Check before making new credit purchases or changing your finances.
A form of ownership where you own your individual lot and share an interest in common property with other owners. It can include apartments and townhouses.
Strata fees contribute to shared expenses. Review the records to understand building upkeep, finances, rules and possible additional charges.
The legal record of ownership and registered interests affecting the property.
An easement, for example, may give someone a right to use part of the land. Ask your legal professional what registered interests mean for your intended use.
A loan secured against the home. You repay it under agreed terms, including interest.
The mortgage payment does not cover every cost of owning. Taxes, insurance, utilities and repairs also need a place in your budget.
A separate legal right to cancel certain residential purchase contracts within a limited period, subject to rules and exceptions. It is different from a financing or inspection subject.
Ask your representative immediately whether it applies, when it ends, how notice must be delivered and what fee is payable. It does not replace property checks.
Your down payment is one part. Here’s how the other payments fit around it.
Your down payment is the part of the price you pay from your own funds. The deposit is paid earlier under the contract and is credited toward the purchase at completion.
This is an arithmetic example, not a minimum-down-payment calculation. Closing costs and adjustments are additional.
A home inspection, specialist report or document order may need to be paid for while you investigate the property. A lender may also require an appraisal to assess its value.
Get a written quote, including taxes. These services can still cost money if the purchase doesn’t go ahead.
“Closing” means finishing the legal and financial steps of buying. The costs can include legal fees, registration and search charges, applicable property transfer tax, and other charges specific to your purchase. Some homebuying expenses are paid earlier.
First-time buyer status does not automatically remove every tax or fee. Eligibility for each exemption or rebate needs to be checked.
Imagine the seller has already paid a bill for a period that continues after you take over. You may reimburse the seller for your share. If an amount remains unpaid, the seller’s share may instead be credited to you. Your legal professional works out the actual dates and amounts.
Assume your agreed share for the remaining period is $900.
This increases the funds you need at closing. It is a share of a prepaid bill, rather than a new service fee.
Simplified property-tax example only. The statement of adjustments can include other items, such as strata fees. The contract’s adjustment date and the bill period matter.
Read your representation agreement with your real estate professional. Ask what remuneration is agreed, what may be paid through the transaction, and whether any amount could be your responsibility. Don’t assume every arrangement is the same.
Ask a mortgage broker or lender about broker, lender, appraisal and other charges that could apply. Request the cost, who pays it and when it becomes payable, in writing.
A useful question: “If this purchase doesn’t complete, which fees would I still owe?”
Include property taxes, insurance, utilities, maintenance and a repair reserve. A strata home usually has regular strata fees; special levies are separate charges that can arise for particular expenses.
Review the property’s actual records and ask what is included in the strata fee. Keep a buffer for costs that change.
Cost references: BCFSA ↗ · Financial Consumer Agency of Canada ↗
Your checklist follows the stage you choose above. Keep the questions handy when you speak with your team.
0 of 4 steps checked for this stage.
Your checklist is saved on this device as you make changes.
The full BC handbook is still here: buyer programs, mortgages, property checks, closing and more. Open just what you need.
You can take this a step at a time. Each stage gives you something useful to check before you move forward.
Start with your finances, arrange financing, then search, compare and offer. Investigate the property before committing. Plan the legal completion and your move separately.
List your debts, total accessible savings and choose a comfortable monthly housing limit. Create a home wish list with essentials, preferences and optional extras.
Arrange financing, inspection, insurance and the records you need. Resolve material questions in writing before removing conditions.
Completion is the legal transfer and funding date. Possession is the date and time you can occupy. Confirm both before booking movers.
What happens, and in what order?
| Stage | Main work | Ready to move on when... |
|---|---|---|
| 1. Prepare | Review savings, credit, income and timing | You know your cash and monthly limits |
| 2. Check programs | Confirm each buyer's eligibility separately | Savings and withdrawal deadlines are documented |
| 3. Arrange financing | Submit documents and compare mortgage terms | You understand your lender's conditions |
| 4. Build your search | Choose areas, property types and non-negotiables | Your search fits your real budget |
| 5. View and compare | Tour homes and review comparable sales | You can explain the home's value and compromises |
| 6. Offer | Negotiate price, dates, deposit and conditions | The accepted contract protects your needs |
| 7. Investigate | Financing, inspection, insurance, title and records | Material concerns are resolved in writing |
| 8. Commit | Remove conditions only when satisfied | You can meet the full purchase obligation |
| 9. Close | Sign legal documents and deliver funds | Transfer and mortgage funding are confirmed |
| 10. Move in | Receive keys, inspect and set up services | You have documented condition and started upkeep |
A sample schedule, not a rule: Spend the first few weeks organizing finances and learning neighbourhoods. The search can take days or months. An accepted resale offer may provide an agreed period for conditions, followed by several weeks before completion. Presales can take years. Choose dates that fit your financing, tenancy and actual move.
Start a buyer folder: Save identification, income records, account statements, pre-approval, property documents, inspection reports, insurance quote, contracts, amendments, receipts and closing statements. Maintain a deadline list with the responsible person beside each task.
Your first five actions: List all debts; total accessible savings; choose a comfortable monthly limit; book a mortgage discussion; create a three-column home wish list: essential, preferred, optional.
0 of 2 next steps checked
Your down payment is one part of the picture. Leave room for the purchase costs, the move and the life you want afterward.
Plan for your down payment, closing costs and move-in expenses, plus a separate reserve. A deposit is generally part of your down payment, rather than an extra amount on top.
Example: if your total down payment is $60,000 and you have already paid a $30,000 deposit, the remaining down payment is normally $30,000. Closing costs and adjustments are additional. Your contract sets the deposit amount and deadline.
Include legal or notary work, inspection, appraisal if required, property transfer tax, applicable GST, adjustments, insurance, moving and setup. Get quotes and ask your conveyancer for the actual amount due.
Add property tax, strata fees where applicable, insurance, utilities and maintenance to the mortgage payment. Test a higher-cost version of the budget and keep a reserve for unexpected expenses.
The lender still needs to approve the property and any outstanding funding requirements. Ask for written confirmation of what remains before removing a financing condition.
Work backward from your monthly budget
Use take-home income for your household budget. Lenders also use gross income for qualification, but gross income is not what reaches your bank account.
| Monthly item | Your estimate |
|---|---|
| Mortgage payment | $________ |
| Property tax, divided by 12 | $________ |
| Strata fee, if applicable | $________ |
| Home or condo insurance | $________ |
| Electricity, heat, water and other services | $________ |
| Maintenance and replacement savings | $________ |
| Parking, commuting and other ownership costs | $________ |
| Total housing cost | $________ |
Add food, transportation, debt payments, subscriptions, recreation, childcare and regular savings. Leave room for the life you want after purchasing.
Run three versions: Your expected cost; a higher-cost version with a larger mortgage payment and utilities; and an income-interruption version. Consider unpaid leave, self-employment variability, a partner's work rotation or a future change in hours. Test whether the purchase still works without overtime or a roommate.
Keep reserves separate. Plan cash for urgent repairs, deductibles and temporary income loss. The right amount depends on income stability, property condition and other support. A condo can still require a special levy; a detached home can require a roof or drainage repair.
Maintenance planning: Price the likely big items instead of relying only on a percentage rule. Identify age, condition, approximate replacement cost and timing for the roof, heating system, hot-water tank, exterior, windows and appliances. In a strata, review both your unit expenses and the building's funding plan.
Practice before buying: For two or three months, save the difference between your current housing expense and your proposed ownership expense. See whether that routine is sustainable before committing.
These are different things
Down payment: Your contribution toward the purchase price. Deposit: Money paid under the purchase contract, generally credited toward your down payment at closing. Closing costs: Other transaction expenses. Reserve: Money you keep after closing.
For a standard eligible owner-occupied purchase, the federal minimum down payment is 5% through $500,000, then 10% of the portion above $500,000 for prices below $1.5 million. At $1.5 million or more, it is 20%. Lenders may require more.
| Price | Minimum down payment | 20% down payment |
|---|---|---|
| $400,000 | $20,000 | $80,000 |
| $500,000 | $25,000 | $100,000 |
| $600,000 | $35,000 | $120,000 |
| $750,000 | $50,000 | $150,000 |
| $1,000,000 | $75,000 | $200,000 |
| $1,400,000 | $115,000 | $280,000 |
| $1,500,000 | $300,000 | $300,000 |
Example: On a $600,000 purchase with $60,000 down and a $30,000 deposit, you normally owe the remaining $30,000 down payment at closing, plus costs and adjustments. The deposit is part of the $60,000, not an additional $30,000.
Deposit logistics: Amount, deadline, recipient and trust arrangements come from the contract. There is no universal deposit percentage. Ask how funds must be delivered and when they must clear.
Document the source: Lenders commonly request an account history and explanations for large deposits. Gifted funds may require a signed gift letter and evidence of transfer. Borrowed funds affect qualification and require lender acceptance. Move money early enough for bank holds and registered-account processing.
Cash equation: Total down payment + closing costs + move-in expenses + reserve = savings target. Subtract the deposit only when calculating the balance still due.
What the lender needs to see
Ask the lender or broker for a document checklist specific to your income type. Avoid relying on an online payment estimate as proof of approval.
Identity and status: Government identification and any required residency documents.
Employment income: Employment letter, recent pay statements, tax slips and notices of assessment. Commission, bonus, overtime, contract or seasonal income may need a longer history.
Self-employment: Personal and business tax records, financial statements and other evidence requested by the lender. Revenue and qualifying income are different figures.
Savings: Account statements, investment statements, gift documents and explanations of significant transfers.
Debts: Credit cards, lines of credit, vehicle loans, student loans, support obligations and any co-signed debt.
Purchase documents: Accepted contract, listing, strata information, appraisal and other property records as requested.
Credit preparation: Pay on time, check your credit report for errors and reduce revolving debt where practical. Ask before closing an account or moving debt. Avoid taking on a car payment, financing furniture, co-signing or changing jobs while your purchase is being approved and funded.
Pre-qualification: Usually an initial estimate based on limited information. Pre-approval: A more detailed review, sometimes with a rate hold. Final approval: Approval of you, the property, the insurer where relevant, and all outstanding funding requirements. Terminology varies by lender.
A rate hold has an expiry date. Ask which rate applies if rates fall, whether the hold can be extended and whether it covers your proposed completion date. A presale completion estimate may extend far beyond it.
Before removing financing conditions: Ask for a written list of outstanding requirements. A promise that the file looks good is different from property-specific approval. Discuss appraisal shortfalls, insurer acceptance, down-payment verification, insurance and any conditions that could still prevent funding.
| Pre-qualify | Pre-approve | Approve |
|---|---|---|
| Initial estimate | Review your finances | Review you + property |
The stress test and debt ratios
Federally regulated lenders generally qualify you at the higher of 5.25% or your contract rate plus two percentage points. Other lenders may also use a stress test. At a 4.50% contract rate, that means testing payments at 6.50%. The qualifying payment is not necessarily the payment you actually make.
Gross debt service (GDS) compares qualifying housing costs with gross income. Total debt service (TDS) adds other debt obligations. Common CMHC benchmarks are approximately 39% GDS and 44% TDS, but lender and insurer requirements differ.
Illustration: Gross household income of $100,000 equals $8,333 per month. At 39%, the initial housing-cost allowance is about $3,250. If property taxes are $300, heat is $100 and the lender includes $250 of a $500 strata fee, approximately $2,600 remains for the qualifying mortgage payment. This is an illustration of the method, not a loan approval.
For TDS, add the payments the lender assigns to your debts. A large unused line of credit, student loan, vehicle payment or co-signed loan may be treated differently by different lenders. Ask how each is calculated.
Suite income: The lender decides whether and how much rental income to count. It may need a lease, market-rent appraisal or proof of legal use. Do not budget as though every dollar of advertised rent will increase your borrowing capacity by the same amount.
Appraisal shortfall: If you agree to pay $600,000 but the lender supports a lower value, your financing may be reduced. You may need more cash, a different lender, a renegotiation or a valid contractual exit. Ask before committing.
Pre-approval can change: A higher strata fee, property problem, reduced income, new debt, interest-rate movement or a delayed completion may change the result. Recheck your file when the property or timing changes.
| Illustrative contract rate | Stress-test comparison | Illustrative qualifying rate |
|---|---|---|
| 4.50% | + 2 percentage points | 6.50% |
Compare the whole contract
Term is the period your mortgage agreement runs before renewal. Amortization is the estimated overall repayment period. Eligible insured first-time buyers and buyers of new builds may access 30-year amortization; a longer amortization generally lowers payments but increases lifetime interest if other factors stay the same.
| Feature | Ask before choosing |
|---|---|
| Fixed rate | How is the early-break penalty calculated? |
| Variable or adjustable rate | Does the payment change, or does principal repayment change? What happens if rates rise? |
| Open or closed | What flexibility do I receive, and what does it cost? |
| Prepayments | How much extra can I pay, when, and without penalty? |
| Portability | Can I move the loan to another home, subject to what approval and timing? |
| Renewal and transfer | What fees and restrictions apply when switching lenders? |
| Registration | Is it a standard or collateral charge, and what are the implications? |
| Fees and cashback | Are there lender, broker, appraisal, discharge or cashback-repayment costs? |
Default insurance: With less than 20% down, it is typically required on an eligible purchase. It protects the lender, not your income or your equity. The premium can often be added to the mortgage. CMHC's standard 25-year premiums include 4.00% at over 90% through 95% loan-to-value, 3.10% at over 85% through 90%, and 2.80% at over 80% through 85%. Home Start's 30-year premiums are higher. Obtain the exact insurer quote.
Different insurance purposes: Home insurance covers property risks under its policy. Default insurance protects the lender. Optional life, disability or critical-illness coverage addresses different risks and has its own exclusions and underwriting.
Ask for a comparison using the same purchase price, down payment, amortization and completion date. Include payment, premium, fees, penalty method and flexibility. The lowest advertised rate may not suit a likely move or early repayment.
Build it line by line
General consumer guidance suggests reserving roughly 1.5% to 4% of price for upfront costs, but that is only a starting point. GST, tax exemptions, unusual legal work and property-specific checks can put your purchase outside that range. Use actual quotes and a conveyancer's estimate.
| Cost | What to confirm |
|---|---|
| PTT | Fair market value, exemption and qualifying ownership share |
| GST | Taxability; included/extra; rebate and credit timing |
| Legal/notary work | Fees, disbursements, registration and taxes |
| Inspection | Base inspection and any specialist follow-up |
| Appraisal | Whether required, cost and who pays |
| Title-related costs | Title insurance, survey or other required evidence |
| Adjustments | Property tax, strata fees and other prepaid expenses |
| Insurance | Premium, start date and required coverage |
| Financing fees | Lender/broker charges, if applicable |
| Buyer brokerage fee | Any amount you owe under your agreement |
| Strata administration | Document, move-in, elevator or deposit charges |
| Moving and setup | Movers, utility deposits, locks and immediate supplies |
| Repairs and reserve | Immediate work plus funds kept after closing |
| Down payment | Closing costs | Reserve |
|---|---|---|
| Your contribution to price | Transaction costs and adjustments | Cash kept after completion |
Cash flow, adjustments and the balance due
Adjustments: If the seller prepaid an expense that covers part of your ownership period, you may reimburse them. If an amount attributable to their period remains unpaid, the statement may provide a credit. Your conveyancer calculates the actual treatment.
Costs paid at different times: Inspections and deposits often happen well before legal completion. The final trust payment then covers the remaining down payment and closing balance, adjusted for amounts already paid and mortgage funds actually advanced.
Do not count the same dollar twice: A rebate already credited in the price cannot also be subtracted as a later cash receipt. A financed default premium increases the loan; it is not a separate cash saving. An income-tax benefit expected next spring is not cash available today.
Ask for two numbers: Total purchase cash across the whole transaction, and the exact remaining amount your legal professional needs by their deadline.
YOUR CASH-TO-CLOSE WORKSHEET
Total down payment
+ Closing costs and adjustments
+ GST to fund, if applicable
+ Move-in expenses
- Deposit already paid
- Other purchase costs already paid
= Remaining purchase cash to fund
Separate reserve to keep after closing
Use the final statement from your conveyancer for the amount and deadline actually due.
Follow the dollars from savings to completion
These are planning illustrations with invented service-cost allowances, not quotes. Both assume full eligibility, personal occupancy and standard property rules. Real adjustments and lender requirements vary.
A. $600,000 resale home, 10% down, 25 years
| Item | Amount |
|---|---|
| Down payment | $60,000 |
| Base mortgage | $540,000 |
| Illustrative CMHC premium at 3.10% | $16,740 |
| Mortgage if premium added | $556,740 |
| Regular PTT less $8,000 exemption | $2,000 |
| Assumed legal, inspection, appraisal, adjustments and setup | $5,000 |
| Total purchase cash, before separate reserve | $67,000 |
If $30,000 has already been paid as a deposit, it is included in the $60,000 down payment. The remaining combined cash need is approximately $37,000, less any of the $5,000 allowance already paid. At an illustrative 4.50% fixed nominal rate compounded semi-annually, the monthly mortgage payment is approximately $3,081, before all other housing expenses.
Illustrative 4.50% fixed nominal rate, semi-annual compounding, 25 years. Other housing costs extra.
A qualifying new-condo illustration
B. $400,000 new condo, 5% down, eligible tax relief
| Item | Amount |
|---|---|
| Down payment | $20,000 |
| Base mortgage | $380,000 |
| Illustrative 25-year CMHC premium at 4.00% | $15,200 |
| Mortgage if premium added | $395,200 |
| PTT with qualifying newly built exemption | $0 |
| GST before coordinated eligible rebate | $20,000 |
| Assumed other purchase costs | $5,000 |
If the full GST rebate is credited at completion, purchase cash is approximately $25,000, before a separate reserve. Without a completion credit, gross GST funding could add $20,000 temporarily; confirm financing and the coordinated rebate. At the same illustrative rate and 25 years, the monthly mortgage payment is approximately $2,187. Strata fees, taxes, insurance and utilities are extra.
Do not subtract FHSA/HBP balances again: They can supply the down payment already shown. They are not an extra discount on the purchase price.
Illustrative 4.50% fixed nominal rate, semi-annual compounding, 25 years. Other housing costs extra.
0 of 3 next steps checked
Different programs solve different problems. Check what each one does, when it helps and whether each buyer qualifies.
Use the program map to separate savings accounts, withdrawals, tax relief and rebates. “First-time buyer” has different definitions across programs, so eligibility needs a separate check for each.
Both can help eligible buyers fund a purchase using their own savings. The FHSA and HBP have different withdrawal, timing and repayment rules. Confirm the details with your account provider before moving money.
These are different taxes with different relief programs. Ask your conveyancer to confirm the property, ownership shares and eligibility. A new-home rebate may be credited at completion or claimed later.
Some benefits reduce costs at closing; others affect a later tax return or require an application. A later refund is not necessarily money you can use to complete the purchase.
Identify what each benefit actually does
| Program or option | Main purpose | When it helps |
|---|---|---|
| FHSA | Deductible saving; qualifying withdrawal tax-free | Saving and purchase funding |
| RRSP Home Buyers' Plan | Access your RRSP, up to $60,000 per eligible person | Purchase funding; repayments later |
| BC first-time buyer PTT exemption | Reduce property transfer tax by up to $8,000 | Title registration |
| BC newly built home PTT exemption | Eliminate or reduce PTT on eligible new homes | Title registration |
| Federal first-time buyer GST rebate | Recover eligible GST on a qualifying new home | Builder credit or later application |
| Home buyers' amount | Non-refundable federal tax credit | Purchase-year tax return |
| 30-year insured mortgage option | Spread repayment over longer period | Monthly payment; higher interest tradeoff |
| CMHC Eco Plus | Refund part of eligible insurance premium | After closing and application |
| BC home owner grant | Reduce eligible annual property tax | During ownership, annual application |
First-time buyer has different definitions. A person can qualify for one program and fail another. BC's first-time PTT program uses a never-owned-and-occupied test. Federal savings and tax programs often use a current-year and previous-four-calendar-year test, with important differences involving a spouse or partner.
Do not treat all benefits as closing cash. A deduction can reduce income tax; a credit offsets eligible tax; a rebate may arrive later; an HBP withdrawal is your own retirement money and normally requires repayment. A longer mortgage is financing, not a grant.
Check each buyer: Previous ownership worldwide; where they actually lived; spouse or common-law history; citizenship or permanent residence; BC residence history; title share; age where relevant; intended occupancy; contract and completion dates; and past use of a program.
Create a written program checklist with the lender, conveyancer and tax adviser. Record the amount, eligibility evidence, application method, expected timing and continuing obligations. Never add two PTT exemptions together against the same tax.
Save with a deduction and a tax-free qualifying withdrawal
An FHSA starts with $8,000 of participation room in the year you first open one. The lifetime contribution and RRSP-transfer limit is generally $40,000; unused participation room carried forward is capped at $8,000. Room starts with opening, not simply with becoming an adult. Contributions are generally deductible; an RRSP transfer uses room without creating another deduction.
Opening age and residence: You must meet CRA's Canadian-residency and age rules; institutions in BC generally require age 19 to enter the account contract. You must be 71 or younger at the end of the opening year.
Illustration: Contributing $8,000 at an assumed 30% marginal tax rate could reduce income tax by $2,400. Your actual result depends on taxable income, deductions and when you claim them. The contribution is your money; the tax saving is the benefit.
Opening versus withdrawing: The eligibility tests differ. When opening, a current spouse's or common-law partner's ownership of a home you lived in can matter. The qualifying-withdrawal test focuses on a home you owned and occupied. Check the exact CRA test rather than assuming one approval covers both.
Withdrawal essentials: Use Form RC725 through the issuer. You need a written purchase/build agreement, the required Canadian residency, intention to occupy within a year, and acquisition or construction completion before October 1 of the following year. You generally cannot have acquired the home more than 30 days before withdrawal. A qualifying withdrawal needs no repayment and has no minimum holding period.
For a couple: Each eligible person can use their own account. That does not create a joint FHSA or automatic eligibility for the other buyer. Ask how withdrawals will arrive and whether funds will be available by the deposit or legal-funding deadline.
Presale timing matters: Signing a contract years before completion does not mean you should withdraw immediately. Compare the withdrawal deadline with the actual expected acquisition date.
When the account ends: Close all FHSAs by December 31 of the earliest applicable year: the 15th anniversary year, the year you turn 71, or the year following your first qualifying withdrawal. If you do not buy, an eligible direct RRSP/RRIF transfer can generally defer tax; arrange it with the issuer rather than cashing out automatically.
Contribution deadline: FHSA contributions use the calendar year; the first-60-days RRSP timing does not give you a prior-year FHSA contribution deduction.
Investment choice: If you need the money soon, consider liquidity, bank holds and the risk of a market drop. Track contributions across all your FHSAs and confirm closing/transfer rules with the issuer after your purchase.
Access retirement savings with a repayment obligation
Eligible buyers can withdraw up to $60,000 each under the HBP and can use it with an FHSA for the same qualifying home. For first withdrawals in 2026 through 2028, CRA currently states that the 15-year repayment period starts in the fifth following year: a first withdrawal in 2026 starts repayments in 2031.
Eligibility and withdrawal: Confirm the first-time test, including a current spouse's or partner's home you lived in; Canadian residency; a written purchase/build agreement; intended occupancy within one year; and acquisition/build deadlines. Some disability and relationship-breakdown rules provide exceptions. Locked-in or certain group accounts may not permit withdrawal.
Use Form T1036 with the RRSP issuer. Recent RRSP contributions can lose deductibility under the 89-day rules; do not assume you can deposit money immediately before withdrawing and receive the intended deduction.
Repayment illustration: A $60,000 HBP balance initially spread over 15 years means a $4,000 annual repayment, approximately $333 per month set aside. Follow the annual minimum shown by CRA; prior extra repayments or other changes affect the amount. Amounts designated as HBP repayments are not ordinary deductible RRSP contributions. An un-repaid required amount is generally included in taxable income.
There is an opportunity cost: Withdrawn money is no longer invested in the RRSP while it is out. Compare using the HBP with using other savings, preserving an emergency fund or making a larger down payment later. The best choice depends on your finances.
For two buyers: If both qualify and have sufficient eligible RRSP assets, the combined withdrawal could be $120,000. That is access to their savings, not a government payment.
Timing checklist: Confirm account access; verify recent contributions; obtain the contract; check deadlines with the issuer; arrange withdrawal processing; retain the T1036; and add the future repayment start year to your ownership budget.
*Illustration for a full $60,000 HBP balance repaid over 15 years.
| Maximum per eligible buyer | General repayment period | Initial annual repayment (illustration) |
|---|---|---|
| $60,000 | 15 years | $4,000 |
The first-time buyer exemption
PTT is separate from annual property tax. General rates are 1% on the first $200,000 of fair market value, 2% from $200,000 through $2 million, and 3% above $2 million, with an additional 2% on the residential portion above $3 million.
For the first-time buyer exemption, generally you must be a Canadian citizen or permanent resident; have lived in BC for the preceding year or filed as a BC resident in two of the last six tax years; never have held a registered interest in a principal residence anywhere; and never have used this exemption/refund. Standard property rules include a principal residence, residential improvements and no more than 0.5 hectares. Move in within 92 days and continue occupying through the first year, subject to exceptions. The conveyancer applies through the PTT return. A non-qualifying co-owner reduces the eligible ownership share.
| Fair market value | Regular PTT | Eligible exemption | PTT remaining |
|---|---|---|---|
| $400,000 | $6,000 | $6,000 | $0 |
| $500,000 | $8,000 | $8,000 | $0 |
| $600,000 | $10,000 | $8,000 | $2,000 |
| $750,000 | $13,000 | $8,000 | $5,000 |
| $835,000 | $14,700 | $8,000 | $6,700 |
| $850,000 | $15,000 | $3,200 | $11,800 |
| $860,000 | $15,200 | $0 | $15,200 |
For a fully eligible standard property, the maximum benefit is $8,000 through $835,000, tapering to zero at $860,000. The $835,000 threshold does not mean no PTT on that whole price. Table assumes 100% qualifying ownership and no land-size or use adjustment.
Before offering: Have your conveyancer confirm fair market value, title shares and use. Acreage, mixed use, a previous home abroad, inherited ownership or adding a parent to title can change the answer. Do not confuse BC's lifetime ownership test with a federal four-year test.
Two different taxes, two different exemptions
BC newly built home PTT exemption: Qualifying homes up to $1.1 million fair market value can receive a full PTT exemption, with a phaseout above that to below $1.15 million. It is not limited to first-time buyers. Citizenship/permanent residence, property qualification, size and use rules apply. Generally move in within 92 days and occupy through the rest of the first year.
GST: A taxable new-home sale in BC generally carries 5% GST. Ordinary used residential sales are generally exempt, but unusual use and transaction structures need tax review. Ask whether the advertised price is before tax, tax included, or net of assigned rebates.
Federal first-time buyer GST rebate: Applications are open. Qualifying new homes up to $1 million can receive a rebate of the full GST, up to $50,000. The maximum rebate tapers between $1 million and $1.5 million; none applies at $1.5 million. It tops up the existing new-housing rebate where applicable, rather than duplicating that refund.
| Tax-exclusive price | GST at 5% | Illustrative FTHB rebate | Net GST |
|---|---|---|---|
| $400,000 | $20,000 | $20,000 | $0 |
| $750,000 | $37,500 | $37,500 | $0 |
| $1,000,000 | $50,000 | $50,000 | $0 |
| $1,250,000 | $62,500 | $25,000 | $37,500 |
| $1,500,000 | $75,000 | $0 | $75,000 |
Illustrations assume full eligibility and a simple builder purchase; lower-price totals include any ordinary federal new-housing rebate component. Do not apply the taper as a percentage of all GST paid above $1 million. Confirm the exact calculation with the legal/tax adviser.
Cash-flow point: If the builder does not credit an eligible rebate, you may need to fund GST at completion and claim later. Get a written statement showing price, GST, each rebate, who receives it and cash required. Never assume eligibility from the words "brand new."
A presale contract date can decide the outcome
For a typical builder purchase, the federal FTHB GST rebate generally requires an agreement entered into on or after March 20, 2025 and before 2031. Construction must start before 2031, be substantially completed before 2036, and ownership transfer before 2036. Eligible buyers are at least 18, citizens or permanent residents, meet the current-year/four-prior-year ownership-and-occupancy test including a spouse or common-law partner, and use the property as their primary residence as first occupant. Prior rebate use by either partner matters.
Earlier presale? A completion in 2026 or 2027 does not fix a contract originally signed before March 20, 2025. Assignment, amendment or cancellation/re-signing is not a reliable route around the original-date and anti-avoidance rules. Get advice on the actual agreement chain.
Applying: For builder purchases, Form GST190 is used. The builder may credit the rebate by agreement; otherwise follow CRA's direct application route. The usual builder-purchase filing deadline is two years after ownership transfers. Owner-built homes use Form GST191 and have different triggering dates.
Co-buyers need special review: Do not assume a parent on title, a non-qualifying partner or a guarantor has no effect. Give the adviser the proposed ownership arrangement before signing or changing the contract.
Ordinary new-housing rebate: This older federal rebate generally provides up to $6,300, phases out between $350,000 and $450,000, and is unavailable at $450,000 or more. It has its own conditions and is not restricted to first-time buyers. If both regimes apply, calculate the coordinated total.
Questions for the developer and conveyancer: What is the original agreement date? Is GST included? Which rebate is already reflected? Will the builder credit it? Who bears the cost if CRA denies eligibility? Can the lender fund the gross amount? What must be signed or retained?
| Original agreement | Construction | Ownership |
|---|---|---|
| Check the signing date | Check required dates | Check transfer and occupancy |
What else should you check?
Home buyers' amount: The federal claim amount is up to $10,000 shared among eligible claimants for one home. It is a non-refundable tax credit, not a $10,000 refund. Eligibility generally includes a current-year/four-prior-year ownership-and-occupancy test and intended occupancy within a year, with disability exceptions. CRA's currently published claim page addresses 2025; verify the purchase year's return. At the general 2026 credit rate of 14%, $10,000 implies about $1,400 of federal tax reduction, subject to available tax and any applicable top-up rules.
BC home owner grant: Annual property tax relief, not down-payment money. For 2026, basic grants are up to $570 in Metro Vancouver, the Fraser Valley and Capital Regional District, and up to $770 elsewhere, including Nanaimo. The threshold is $2.075 million before phaseout; higher grants may apply to eligible seniors, veterans or disability situations. Apply annually and confirm eligibility.
CMHC Eco Plus: Eligible CMHC-insured purchasers of qualifying new energy-efficient homes can apply for a 25% insurance-premium refund within two years of mortgage closing. Documentation of energy performance is required. Do not assume that a heat pump alone establishes eligibility. Other insurers have their own offerings.
Local and targeted assistance: Check official municipal and BC Housing listings for any project-specific affordable ownership or resale-restricted opportunities. Inventory, income limits, residency rules, financing conditions and resale formulas can matter. Disability-related adaptations and energy upgrades have separate assistance streams; confirm availability before starting work. These are not a universal first-time buyer cash grant.
Do not rely on old articles: The federal shared-equity First-Time Home Buyer Incentive stopped new submissions March 21, 2024. BC HOME Partnership stopped new applications March 31, 2018. Neither is an available new down-payment application today.
Stack carefully: FHSA and HBP can work together when both qualify. PTT relief and eligible GST relief address different taxes. None of this guarantees the bank will lend more.
0 of 3 next steps checked
Picture an ordinary day here. Then look past the staging to the layout, condition and costs.
Compare location, function and condition separately. Take notes after each viewing, and identify which questions need documents, quotes or a professional inspection.
Consider storage, stairs, working from home, parking, pets and carrying groceries inside. Visit the neighbourhood at different times when practical.
Ask about heating, the roof, hot-water tank, moisture, drainage and significant repairs. Answers help guide your investigation; a viewing does not replace an inspection.
Separate essentials from preferences. Include likely repairs and ongoing expenses, rather than comparing the asking prices alone.
Build a search that teaches you something
Set the brief: Price cap, monthly cost cap, move date, preferred areas, property type, bedroom count, work space, parking, pets, accessibility, outdoor space and must-have transit or school access. Separate a practical need from a finish you can change.
Search broadly enough: Use REALTOR.ca, brokerage searches, agent alerts, open houses and developer sites. Ask for alerts that include price changes and back-on-market listings. Online estimates, assessed values, asking prices and sold prices answer different questions.
Learn the actual market: Compare recently sold similar homes with current competition. Match tenure, location, building condition, size, lot, parking, age and strata health. A lower price per square foot can reflect a costly building issue or a less useful layout. Ask what explains each price difference.
Review the whole listing: Confirm legal property type, tenure, tax figure, strata fee, floor area source, parking arrangement, age restrictions, included items and whether GST is extra. Marketing language such as "suite potential," "ocean view" or "development opportunity" needs independent checking where important.
Neighbourhood research: Visit on a weekday, in the evening and when it rains. Try the commute, parking and route to groceries. Listen for traffic, commercial activity, aircraft or neighbours. Review nearby development applications, zoning, construction and future infrastructure with the local government.
Vancouver Island lens: Consider hills and winter access, ferry or highway dependence, wildfire exposure, coastal wind and salt, drainage in wet weather, well/septic service outside town, and access to contractors. A view from today's deck does not guarantee a protected view.
Use a simple comparison sheet: Address; asking price; likely all-in monthly cost; three strengths; three compromises; documents missing; repair concerns; and next action. Keep the same criteria for every home.
After the first five viewings, refine the search. If every suitable home exceeds the budget, change location, size, property type or timing before stretching the mortgage.
Know who is working for whom
Buyer's real estate professional: Helps identify options, evaluate comparable sales, arrange viewings, negotiate and coordinate documents and deadlines. Ask about local experience, property-type experience, communication and conflicts. Confirm representation before sharing your maximum budget or bargaining position with someone working for the seller.
Buyer agency agreement: Read service scope, area, duration, exclusivity, cancellation terms, remuneration, any seller-paid contribution, possible shortfall and when payment becomes due. Commissions are negotiable; do not assume buyer representation can never cost you directly.
Mortgage broker or lender: Assesses financing options and property requirements. Ask which lenders are considered, how compensation works, whether fees apply and what assumptions underlie the approval.
Lawyer or notary: Handles conveyancing and advises within their professional scope. A lawyer may be needed for complex title, co-ownership, tenancy, tax or contractual issues. Choose early, confirm availability and get a fee/disbursement estimate.
Inspector and specialists: A general inspection can identify concerns and recommend further investigation. Structural, electrical, septic, drainage, geotechnical and environmental questions may require separate experts.
Insurance broker: Checks whether the property can be insured on acceptable terms. For condos, review strata deductibles and your personal coverage. For houses, discuss age, heating, electrical, plumbing, vacancy and hazard exposure.
Accountant/tax adviser: Useful for uncertain rebate eligibility, ownership changes, a suite, self-employment, a prior property or plans to sell quickly.
Questions when choosing professionals: What will you review? What is outside your scope? What do you charge? Can you meet this deadline? Will I receive findings in writing? What would cause you to recommend a specialist?
Request written conclusions for material issues and make sure someone owns each unresolved task. A referral does not replace your own evaluation of the person's qualifications and service.
Start with function and condition
Outside: Roof shape and apparent wear; gutters; grading; standing water; retaining walls; foundation cracks; exterior cladding; decks; stairs; railings; driveway and site access. Ask about previous leaks, repairs and permits. A viewing is not an inspection.
Inside: Layout, usable room sizes, storage, light, privacy, smells, ceiling stains, cracks, sloping floors, sticking doors, visible moisture and ventilation. Check whether furniture will fit and whether bedrooms meet your practical needs. Measure important spaces rather than trusting a wide-angle photo.
Systems: Ask age and service history of heating/cooling, hot-water tank, electrical panel and plumbing. Ask what fuels are used and whether any rented equipment or service contracts exist. Request utility costs while recognizing that occupancy and habits affect them.
Condo or townhome: Listen between rooms and from neighbouring units. Check elevator access, garbage and recycling, bike storage, visitor parking and route from your stall. Confirm the exact parking and locker identifiers in records. Look at common areas for deferred maintenance.
Daily life: Where do coats, shoes, sports equipment and a vacuum go? Where will you work? Can you get groceries upstairs? Can your pet use the space? How hot might the unit become? Can you safely access the home in winter?
Ask, then verify: Why is it selling? How long has it been listed? Any offers or price changes? Known water damage? Work completed without permits? Upcoming strata projects? Relevant documents available? Treat answers as leads for investigation.
Watch for pressure: Fresh paint does not establish sound construction. Staging is not included unless written in the contract. A busy open house does not establish market value. If an issue materially affects your decision, identify what evidence would resolve it before you offer.
After the tour: Write your notes immediately. Rate condition separately from style and location. Price the changes you would actually make; a cosmetic bargain can become expensive if the underlying systems need replacement.
| Location | Function | Condition |
|---|---|---|
| Daily life and surroundings | Layout, access and storage | Systems, moisture and repairs |
0 of 2 next steps checked
The price matters. So do the dates, deposit, included items and time to investigate.
Review the whole offer before signing. Understand each condition, its deadline and what happens when it is satisfied or waived. Resolve important uncertainties before committing.
Confirm legal names, price and tax treatment, deposit, completion, possession, adjustments, inclusions and conditions. Ask about any clause you cannot explain in your own words.
Send the contract to your lender, book inspections, arrange insurance and request the necessary records. Keep a written list of outstanding questions and deadlines.
They are separate routes with different requirements and consequences. Have your representative or lawyer explain the applicable rules, notice process and deadlines for your transaction.
Negotiate the full package
An offer sets out more than price. Have your representative explain each clause and the effect of acceptance. Ask a lawyer about unfamiliar or material terms before signing.
| Offer element | What to decide |
|---|---|
| Buyer names | Correct legal names; intended ownership arrangement |
| Property | Correct legal description and included interests |
| Price and taxes | GST included/extra; any assigned rebate assumptions |
| Deposit | Amount, deadline, recipient and acceptable delivery |
| Completion | Date title transfer and funds are due |
| Possession | Date and exact time you receive the right to occupy |
| Adjustments | Date ongoing expenses are apportioned |
| Inclusions/exclusions | Appliances, blinds, fixtures and specific items |
| Conditions | Financing, inspection, records, insurance and other needs |
| Other terms | Access, repairs, vacancy and document delivery |
| Acceptance deadline | Exact expiry time for the offer |
| Completion | Possession | Adjustments |
|---|---|---|
| Legal transfer and funding | The date and time you occupy | Apportion ongoing expenses |
Negotiate with a clear ceiling
Price strategy: Use comparable sales and property-specific risk. Decide your comfortable first offer, likely negotiating range and absolute ceiling before discussions. Leave room for repairs and closing costs.
Counteroffers: Review every change. A counter can alter dates, conditions or included items as well as price. Keep a complete signed record of all accepted terms and amendments.
Multiple offers: Decide whether you can safely compete on dates, deposit or price while preserving essential investigation. Do not assume the right home requires waiving every condition. A subject-free accepted offer creates serious exposure if financing or the property later fails your needs.
Inclusions: Describe important items precisely. Do not depend on a photograph to establish that a wall-mounted cabinet, EV charger, hot tub, spare fridge or shelving is included. Clarify leased equipment and ownership of installed items.
Before sending: Read the legal names, dollar figures, dates, condition wording, GST treatment and exclusions aloud. Verify that your deposit is accessible and that everyone signing understands the obligation.
| Evidence | Protection | Discipline |
|---|---|---|
| Use comparable sales | Understand your conditions | Set your maximum offer |
Due diligence needs time and access
Conditions, often called subjects, should match the property and buyer. Common topics include financing, inspection, insurance, title, property disclosure, strata records, permits, water/septic and sale of an existing home. The wording controls what is required, whose benefit it protects and how it is satisfied or waived.
During the condition period: Book inspections immediately; send the contract and property records to the lender; obtain an insurance quote; request all records; have title reviewed; and list unresolved issues. Ask for an agreed extension before the deadline if needed. An extension is not automatic.
If a problem appears: Options may include specialist review, a written repair agreement, a price change, an extension or ending the agreement where the contract permits. The seller need not agree to renegotiate. A repair agreement should address scope, contractor, permits, proof and timing.
BC Home Buyer Rescission Period: Many residential purchases have three business days after acceptance to rescind, with a 0.25% price-based fee. At $600,000, that fee is $1,500. The right cannot be waived and runs alongside conditions, not after subject removal. The next full business day starts the count; holidays can change the deadline. Have notice served correctly and on time.
Exclusions and limitations: Certain leased-land/leasehold, auction and court-supervised transactions are excluded. Presales covered by REDMA have a separate cancellation framework. The rescission right does not itself guarantee access for inspection.
Different exit routes have different consequences: A properly exercised condition can have a different result from statutory rescission. Do not assume a failed condition automatically creates the rescission fee. Have your representative or lawyer confirm the appropriate procedure.
Before removing conditions: Confirm financing, insurance, inspection and documents are satisfactory; resolve material questions in writing; verify your closing cash and dates. Once committed, walking away can expose you to losses beyond the deposit. Get prompt legal advice if completion is in doubt.
| Illustrative purchase price | Statutory rescission fee | Illustrative fee |
|---|---|---|
| $600,000 | 0.25% | $1,500 |
0 of 3 next steps checked
A home comes with a building, a location and legal obligations. Give each the attention it needs.
Match your investigation to the property. Financing, insurance, title and condition all matter. For a strata, review the shared finances and records as well as the unit.
Request current strata records, including the Form B, bylaws, budget, financial statements, meeting minutes, insurance and depreciation report. Look for repeated issues, major work and how it will be funded.
The monthly fee supports shared expenses. A special levy is an additional contribution for a particular purpose. A low fee alone does not establish that the building has a sound funding plan.
Consider the inspection, drainage, permits, title, servicing and insurance. Specialist checks may be appropriate for the age, site and inspection findings. On Vancouver Island, ask specifically about wet-season drainage and building-envelope maintenance.
Get legal review of the contract and disclosure documents. Understand deposit timing, completion changes, financing risk, GST treatment and warranty coverage.
You are buying into a shared financial system
A condo, townhome, duplex or bare-land development may be strata property. Small size or a low fee does not eliminate common obligations. Identify the strata corporation and any separate section.
Request: Current Form B and attachments; registered strata plan; bylaws and rules; current budget; recent financial statements; meeting minutes; insurance documents; depreciation report; engineering or building-envelope reports; special-levy information; litigation details; and relevant alteration approvals. BCFSA's sample document clause includes meeting minutes for the preceding two years.
Form B: Check the unit's fees, amounts owing, alteration agreements, reserve information, litigation and the parking/locker arrangements. Confirm it is current; a certificate obtained at listing may no longer describe the situation accurately.
Read the minutes for patterns: Repeated leaks, insurance claims, elevator outages, drainage concerns, stalled maintenance, collections problems, disputes, shortfalls and recurring owner complaints. Look for the decision and the cost, not only the fact a topic was discussed.
Depreciation report: Shows anticipated long-term common-property work and funding scenarios. Compare the selected funding approach with actual contributions. For stratas with five or more lots, BC now requires a five-year reporting cycle. Transition deadlines differ: certain Metro Vancouver, Fraser Valley and Capital Regional District stratas had July 1, 2026 deadlines; other areas, including Nanaimo, generally have July 1, 2027 transition deadlines for missing/older reports. Confirm the exact category.
A report is a planning tool: It is not a guarantee against defects or special levies. Check its date, assumptions, excluded assets, major projects and whether completed work has changed the forecast.
Ask before removal: Are more documents outstanding? Is an upcoming meeting considering a levy or major repair? Has a specialist explained any technical report? Does the lender or insurer require additional information? A thick document package can still omit the very issue that matters.
| Records | Funding | Risk |
|---|---|---|
| What has happened? | How will work be paid for? | What remains unresolved? |
Look beyond today's monthly fee
Operating fund: Pays recurring expenses. Contingency reserve fund: Supports qualifying longer-term expenses. Special levy: A separately approved contribution for a particular purpose. A healthy building needs a credible plan to fund its work, not just a low monthly fee.
Questions for financial review: What does the fee cover? Are utilities included? How much do fees change in the proposed budget? Are owners behind in payments? Are actual costs above budget? What major work is expected in the next five to ten years? Does the reserve plan plausibly fund it?
Special levies: Ask for approved and proposed levies, total cost, your strata lot's allocation, due dates and payment status. Have the purchase contract and conveyancer establish responsibility between buyer and seller. Do not rely on a verbal statement that the seller will pay.
Insurance: Obtain the strata policy summary and deductibles, then have an insurance broker quote your personal condo policy. Discuss unit improvements, contents, liability, additional living expense, loss assessment and coverage connected to strata deductibles. A large deductible can produce a large personal exposure depending on the circumstances and coverage.
Use restrictions: Read current bylaws for pets, smoking, noise, flooring, renovations, move-in arrangements, parking, EV charging and permitted use. Provincial legislation limits some bylaw powers, but do not assume your intended use is allowed. Short-term rentals require separate review of provincial and local rules.
Parking and storage: Identify whether spaces are part of the strata lot, limited common property, common property under allocation, or held through another arrangement. Verify identifiers, use rights and transferability from the legal records, Form B and relevant agreements.
Small or bare-land stratas: Confirm who pays for roads, water, sewer, retaining walls, exterior maintenance and insurance. A detached appearance can hide shared infrastructure obligations. Ask how decisions are made if owners disagree and whether there is a functioning budget, records system and insurance plan.
| Operating | Reserve | Levy |
|---|---|---|
| Everyday strata expenses | Long-term common costs | A separate contribution |
Inspect the site as well as the building
General inspection: Hire a qualified licensed inspector and agree on scope. Attend where practical and ask what could not be accessed. A visual inspection cannot establish every concealed defect or guarantee future performance. Follow up on recommendations rather than treating the report as a pass/fail certificate.
Possible specialist checks: Sewer camera; perimeter drainage; roof; electrical; plumbing; structural engineering; pests; moisture; oil tank/environmental risk; retaining walls; well yield and quality; septic condition and records; geotechnical slope stability. Choose checks based on age, site, records and findings.
Title and use: Have a legal professional review title, charges, easements, covenants and rights of way. A charge can affect where you build, access, maintenance or use. A survey or other appropriate evidence may be needed for boundary and encroachment questions.
Permits: Verify significant additions, decks, conversions and suites with the local government. A finished space, separate meter or advertised rental income does not prove legal authorization. Confirm what can actually be insured, financed and occupied.
Zoning: If gardening, chickens, a home business, a suite, subdivision or future construction matters, check the property's actual zoning, lot conditions and applicable restrictions. Provincial housing reforms do not automatically establish that a specific project is feasible on your lot.
Hazards and servicing: Investigate flood, wildfire, coastal exposure, steep terrain, contaminated sites and road access where relevant. Verify water, sewer/septic, stormwater, garbage and maintenance responsibilities. Obtain insurance terms before committing.
Disclosure: Read the Property Disclosure Statement critically and ask written follow-up questions. Seller knowledge may be limited. An unanswered item is not proof that a problem does not exist.
Repair estimate: Separate urgent health/safety or water issues, work needed within a few years, and optional cosmetic improvements. Obtain credible quotes for expensive concerns. A negotiated discount only helps if you can fund and manage the work after closing.
| Building | Site | Rights |
|---|---|---|
| Inspect the structure and systems | Check access, hazards and services | Review title, permits and use |
A future home carries different risks
A presale purchase commits you today to complete later under the contract. Your future income, appraisal, lending rules and interest rates may differ from today's assumptions. A reservation or pre-approval does not remove those risks.
Before signing: Have a lawyer review the contract, disclosure statement and amendments. Understand the deposit schedule, trust or permitted deposit arrangements, outside completion date, extension rights, termination rights, size/layout changes, substitutions, assignment rules and fees, default remedies, GST and rebate assumptions.
Separate cancellation regime: Under REDMA, covered presales generally provide seven days to cancel without penalty after the later of signing and acknowledging a reasonable opportunity to read the disclosure statement. Confirm the exact trigger and service process with counsel.
Financing plan: Budget for a higher rate, a lower appraisal, changed employment, delayed completion and a lender requiring more cash. Keep an accessible completion reserve. Do not withdraw FHSA/HBP money years early without checking the program deadlines.
Builder checks: Search BC Housing's builder and New Homes registries. Confirm licensing, warranty enrollment or a valid exemption. Review the developer's completed projects, contractual commitments and the actual warranty policy.
Warranty basics: Minimum 2-5-10 coverage has detailed limits: first-year or 15-month materials/labour periods for certain components, 24-month specified systems, five-year envelope and ten-year structural coverage. The slogan does not mean every defect is covered for two years. Coverage starts can differ between your unit and common property.
Before handover: Review occupancy authorization, completion notice, walkthrough, deficiency list, appliances, finishes, manuals, access devices and warranty reporting procedure. A deficiency list does not necessarily let you postpone completion or hold back funds; the contract and legal advice govern.
Compare incentives on net value: A heat pump, EV stall, upgrade allowance, rate promotion or credit may help, but confirm exactly what is included, taxes, conditions, expiry and lender treatment. Judge the whole price and ongoing cost against alternatives.
Two situations needing early legal review
A sale does not automatically end a tenancy. If you need vacant possession, review the lease, legal notice procedure, timing, compensation and contract terms before offering. Do not assume the seller can simply ask the tenant to leave.
For qualifying purchaser occupancy, BC currently uses a three-month notice with 21 days for tenant dispute. The seller can serve the prescribed portal-generated notice after sale conditions are satisfied and the purchaser has made the required written request. Compensation and good-faith occupancy obligations apply; eligible purchaser/family occupancy generally must last at least 12 months. Fixed terms, service dates and disputes can affect timing.
Ask the lender whether occupancy timing meets its requirements. Obtain legal advice on the purchase clause and the consequence if vacancy is delayed. A contract promise does not extinguish a tenant's statutory rights.
Buying with a partner, friend or parent: Put the arrangement in writing before closing. Discuss down-payment contributions, ownership shares, mortgage payments, repairs, taxes, strata levies, use of space, breakup, death, buyout formula and sale procedure.
Title and mortgage are different: A guarantor, co-borrower and registered owner have different roles. Loan documents can make borrowers responsible for more than their informal share. Adding a parent to title can change tax and program results. Have the lender and legal adviser coordinate the intended structure.
Ownership form: Ask counsel to explain joint tenancy and tenancy in common, including survivorship and estate implications. Match the legal structure to your actual intention, not a generic recommendation.
If status or residency is unusual: A newcomer may still have financing options, while tax exemptions and purchase restrictions use separate tests. Have counsel verify federal non-Canadian purchase rules and any additional BC PTT before signing. Do not equate mortgage approval with permission to purchase or exemption eligibility.
Protect both buyers: Keep records of contributions and gifts, discuss insurance and wills, and document what happens if one person cannot pay or wants to sell.
0 of 3 next steps checked
A clear list of people, tasks and deadlines makes the final stretch easier to manage.
Coordinate your lender, conveyancer, insurance and moving arrangements. Confirm the final funds, legal completion and key-release process. Completion and possession can be different dates.
Get the exact trust amount and deadline from your conveyancer. Allow time for investment sales, registered-account withdrawals and bank holds. Independently verify payment instructions using a known phone number.
Confirm the home is vacant as agreed and included items are present. Document material damage or missing items promptly. Locate shutoffs and collect keys, remotes and fobs.
Keep a home file, compare actual expenses with your budget and start a maintenance calendar. Record warranty dates and arrange any inspection-recommended urgent work.
Keep the file fundable
Immediately after commitment: Deliver the complete signed agreement and amendments to your conveyancer and lender. Confirm legal names, contact details, possession time and who will arrange keys. Keep the deposit receipt.
Financing: Satisfy every remaining lender instruction. Maintain employment, credit and accessible funds. Tell the lender immediately if anything changes. Confirm mortgage advance amount, payment schedule, tax collection arrangements and whether fees are withheld from the advance.
Insurance: Arrange the start date and coverage required by the contract and lender, often beginning on completion. Confirm with the conveyancer rather than assuming possession day is correct. For stratas, have your broker review building coverage and your unit policy.
Legal work: Ask about identification, signing arrangements, title review, mortgage instructions, PTT/GST treatment, exemptions, title insurance and the final statement of adjustments. Buyers outside BC need early planning for acceptable execution and identification.
Funds: Obtain the exact trust amount and deadline. Arrange FHSA/HBP withdrawals, investment sales and transfers early enough to clear. Independently verify payment instructions by calling a known number; do not act on an unexpected email changing bank details.
Moving: Set up electricity and any natural gas service, water/municipal accounts where applicable, internet, address changes and movers. For strata homes, book the elevator, complete forms and pay required move charges. Utilities do not reliably transfer into your name automatically.
Final check: Review agreed repairs and any permitted pre-completion inspection. Confirm the process for documenting problems. Do not assume you can withhold money or refuse completion over a minor deficiency without legal advice.
Completion versus possession: Completion is the legal transfer/funding date. Possession is the contractual date and time you can occupy. They can differ. Arrange movers around confirmed key-release timing and allow for delays.
Before completion day, have one written list showing who confirms funding, who confirms registration, who releases keys and whom to call if an issue occurs.
Check, document and secure the home
Wait for confirmation that keys can be released. Bring the contract's inclusion list, a phone/camera and your inspection notes.
Check that the property is vacant as agreed and document general condition.
Confirm included appliances, fixtures, remotes and other written items are present.
Check agreed repairs and retain any promised receipts or warranty information.
Photograph material damage or missing items immediately and contact your representative.
Locate water shutoff, electrical panel, gas shutoff where relevant and emergency exits.
Check utilities and test essential systems safely. Report an urgent leak or hazard promptly.
Collect door keys, mailbox keys, fobs, garage remotes and parking/storage access.
Confirm mailbox number/location, garbage schedule and any strata contacts.
Change locks or access codes where appropriate, respecting strata requirements.
Test smoke and carbon monoxide alarms; review emergency equipment.
If something is wrong: Document before changing it where safe. Notify your representative and legal professional promptly. Follow emergency mitigation advice for active damage. Do not assume a post-closing complaint automatically leads to reimbursement; remedies depend on the facts and contract.
Create a home file: Closing statement, title records, mortgage details, insurance policies, inspection, manuals, service records, strata contacts and warranty information. Record model numbers and dates for major appliances and systems.
For a new home: Keep the walkthrough deficiency list, developer contacts, warranty provider and policy. Record claim deadlines from the policy. A verbal promise at handover should be followed up in writing.
For a condo: Learn water-shutoff procedures, emergency contacts, elevator booking, recycling, parking and guest rules. Introduce yourself to the property manager and confirm how notices and meeting packages are delivered.
During the first week: Check for leaks under fixtures, ensure ventilation is working, learn your thermostat and arrange any inspection-recommended urgent work. Keep the emergency reserve available while you learn the home's actual costs.
Turn the purchase into a manageable routine
First month: Confirm mortgage payments, utility billing and insurance documents. Create a maintenance calendar. Compare actual expenses with your budget and adjust the monthly reserve.
Tax and program follow-through: Apply annually for any eligible BC home owner grant; it is separate from arranging mortgage tax payments. Retain evidence for PTT occupancy requirements and federal rebates. Claim eligible purchase-year tax credits, track FHSA reporting and arrange HBP repayments when due. Apply for an eligible Eco Plus refund within its deadline.
Home maintenance: Service heating and ventilation as directed, maintain filters, check drainage and gutters, look for leaks, and inspect exterior seals and decks. On Vancouver Island, wet-season drainage and building-envelope upkeep deserve regular attention. Follow specialist advice for your property.
Strata participation: Read notices and minutes, attend meetings and review budgets and major projects. Keep personal condo insurance aligned with strata policy changes. A special levy is easier to manage if you understand the project before the payment is due.
New-home warranty: Diary relevant reporting dates. Keep dated photos and send written notices through the prescribed process. Understand that unit and common-property coverage may begin at different times.
If plans change: Renting out the home, adding an owner, moving out or selling can affect exemptions, insurance, financing and tax. Ask before acting, especially during required occupancy periods.
Selling quickly: BC's home flipping tax can apply to profit from a sale, including a presale assignment, when held less than 730 days. Its rate is 20% within the first 365 days and then declines; exemptions and filing requirements matter. Living in the property does not create a blanket exemption. Federal tax rules also need separate review.
Year-end review: Recheck your household budget, insurance, emergency fund and future repair costs. Keep a reminder for mortgage renewal well ahead of the term end so you have time to compare options.
| Monthly | Seasonally | Annually |
|---|---|---|
| Budget, reserve and records | Inspect and maintain | Taxes, insurance and review |
0 of 3 next steps checked
Keep your financial limits, home brief and unanswered questions together. Give each next action a person and a deadline.
Before committing, confirm the financing, property checks, insurance, tax treatment, closing funds and deadlines. Keep material answers in writing.
Use the commitment checklist below with your representative and legal adviser. Resolve missing documents and unanswered questions before the deadline.
Use these before committing
MY FINANCIAL LIMITS
Comfortable all-in monthly housing cost
Purchase cash after preserving a reserve
Reserve remaining after closing
Lender-approved price for this property
My maximum offer without changing the plan
MY HOME BRIEF
Preferred locations
Essential needs
Acceptable compromises
Reasons I would walk away
MY PROGRAM RECORD
| Program | Eligible buyer(s) | Amount / timing | Who confirms? |
|---|---|---|---|
| FHSA | — | — | — |
| HBP | — | — | — |
| PTT relief | — | — | — |
| GST rebate | — | — | — |
| Tax credit / other | — | — | — |
Your final commitment checklist
Written property-specific financing confirmation, with remaining funding requirements understood.
Satisfactory inspection and specialist follow-up, or a documented understanding of risks accepted.
Acceptable insurance terms and costs.
Title, disclosures, permits and intended-use questions reviewed.
Strata documents, funding, insurance and levies reviewed where applicable.
GST, PTT and rebate treatment confirmed with the appropriate adviser.
Deposit, remaining cash, deadlines and completion arrangements verified.
Material uncertainties resolved in writing.
MY NEXT ACTIONS
| Action | Responsible person | Deadline |
|---|---|---|
| — | — | |
| — | — | |
| — | — |
QUESTIONS TO RESOLVE BEFORE I SIGN
0 of 3 next steps checked
Buying a home introduces a lot of unfamiliar language. You should feel comfortable asking for an explanation.
Start with the terms below. If a cost or contract clause remains unclear, ask your representative or legal adviser before signing.
The allocation of certain expenses between seller and buyer, calculated as part of closing.
Amortization is the estimated overall mortgage repayment period. The term is the period of the current mortgage agreement before renewal.
Completion is the contractual legal-transfer and funding date. Possession is the contractual date and time the buyer can occupy.
An additional strata contribution approved for a particular purpose.
The legal process of transferring ownership of a property.
Core purchase and financing terms
| Term | Meaning in a purchase |
|---|---|
| Adjustment | Allocation of certain expenses between seller and buyer |
| Amortization | Estimated total mortgage repayment period |
| Appraisal | Lender-related opinion of property value |
| Assessment | Tax-assessment value; not necessarily today's sale value |
| Completion | Contractual legal-transfer and funding date |
| Condition/subject | Contract requirement with specific satisfaction/waiver rules |
| Conveyancing | Legal process of transferring property ownership |
| Deposit | Contract payment usually credited toward the price |
| Down payment | Purchase-price contribution from the buyer |
| Easement/right of way | Registered rights affecting use of land |
| Equity | Property value less debt secured against it |
| Firm purchase | Purchase with conditions removed/satisfied or none included, subject to applicable rights |
| Form B | Strata information certificate and required attachments |
| Form F | Strata certificate of payment used in transfer process |
Title, rights and ownership terms
| Term | Meaning in a purchase |
|---|---|
| Freehold | Ownership interest in land, subject to applicable restrictions |
| Leasehold | Interest based on a lease rather than the land's freehold title |
| Lien/charge | Legal claim or registered interest affecting title |
| Loan-to-value | Loan compared with the value used for lending |
| Possession | Contractual date/time for the buyer to occupy |
| PTT | BC property transfer tax, separate from annual property tax |
| Rescission | Cancelling under an applicable legal right |
| Special levy | Additional strata contribution approved for a purpose |
| Strata | Individual ownership combined with shared-property obligations |
| Term | Current mortgage agreement period before renewal |
| Title | Registered record of property ownership and interests |
| Underwriting | Lender/insurer review of borrower and property risk |
One useful rule: If you cannot explain a material cost, clause or condition in your own words, ask for an explanation before you sign or waive it.
0 of 1 next steps checked
Prepared for owner-occupied purchases in BC. Rules and lending policies can change. Confirm eligibility, costs, contract terms and deadlines with your lender, conveyancer or tax adviser. Worked examples are illustrations, not quotes or financing approvals.
A useful first conversation
We can help make the search smaller, clearer and more useful from the beginning.